Local Irvine & Orange County · 6 min read
Living Near San Diego Creek: What Irvine Homeowners Should Know About Flood Risk and the 100-Year Plain
Being outside a FEMA hazard area is not the same as being safe in a hard storm. Here is why, and what to do about it.
Short answer
San Diego Creek drains a large upstream watershed through Irvine to Upper Newport Bay. Properties near the creek and its tributary channels carry real exposure during extreme storms — and standard homeowners policies exclude flood entirely. FEMA mapping is a starting point, not a full picture, because urban drainage-capacity flooding is poorly captured by it.
San Diego Creek drains a large part of central Orange County — including most of Irvine — into Upper Newport Bay. Orange County Public Works maintains the channel network that carries it, and in a normal season the system does its job without anyone thinking about it.
The pressure comes in a major event, when the channels are running high and the local storm drains are simultaneously at capacity. That is when water backs up at low points instead of moving through, and that is when we get busy.
How the System Works
Irvine's stormwater moves through a network of engineered channels — San Diego Creek and its tributaries, including Peters Canyon Wash and Bee Canyon — toward Upper Newport Bay and the ocean.
Those channels are sized for design storm events based on historical rainfall. Within that design capacity, they perform. The problem arises when an atmospheric-river event delivers rainfall intensity above what the local storm drain network can move into the channel, or when the channel is already running high from an earlier band.
Irvine averages about fourteen inches of rain a year and almost all of it arrives between November and March, increasingly in concentrated events. That pattern — long dry stretch, then everything at once — is exactly what stresses a drainage system.
What UCI Research Says About Flood Models
Researchers at UC Irvine have published work arguing that widely used private flood risk models understate flood exposure in urbanized Southern California.
The core argument is about mechanism. Many models are built primarily around riverine flooding — a channel overtopping its banks. In a densely urbanized watershed like this one, a great deal of actual flooding is driven instead by drainage capacity: storm drains that cannot accept water fast enough, so it ponds and finds a path across the surface.
That mechanism does not necessarily produce a FEMA special flood hazard area designation, which means a property can be at genuine risk while sitting outside a mapped zone.
This matches what we see on the ground. The Irvine properties that take water in a hard storm are frequently not near the creek at all.
Standing water right now? Call us before you do anything else.
We are on site within 60 minutes anywhere in Irvine, 24 hours a day.
What Actually Floods in Irvine
Homes at the bottom of a grade, where surface water from a whole block converges.
Homes with a driveway pitched toward the garage. This is the single most common entry point we see in a storm event, and it is entirely a grading issue.
Homes where decades of added mulch and planter beds have raised the finished grade above the slab edge, so water arriving at the wall has a downhill path indoors.
Properties with blocked area drains, which in Irvine tract homes silt up over eight dry months and get covered by planting.
Ground-floor units in attached communities, where water crossing a landscaped area reaches a threshold that sits close to grade.
Check your address on the FEMA map
The Flood Map Service Center at msc.fema.gov gives the official designation for your parcel.
Walk your lot in a light rain
Watch where water actually goes. It is more informative than any map for your specific property.
Clear every area drain in October
Before the first storm, not after it.
Check your finished grade
Soil should slope away from the house. Decades of added planter soil quietly reverses that.
Your Insurance Almost Certainly Does Not Cover This
Standard California homeowners policies exclude flood entirely — surface water, storm runoff, rising water, channel overflow, and mudflow. All of it.
That requires a separate flood policy, through the NFIP or a private flood carrier, and NFIP policies generally carry a 30-day waiting period from purchase. You cannot buy it when the storm is in the forecast.
Outside a mapped hazard area, premiums are often surprisingly low. Given what UCI's research suggests about model coverage of drainage-driven flooding, that is worth pricing even if you are confident you are not in a flood zone.
The distinction that does get covered: if a storm damaged your structure — wind lifted roof tiles — and rain entered through that opening, that is generally a covered homeowners claim, because wind created the opening.
What to Do Before November
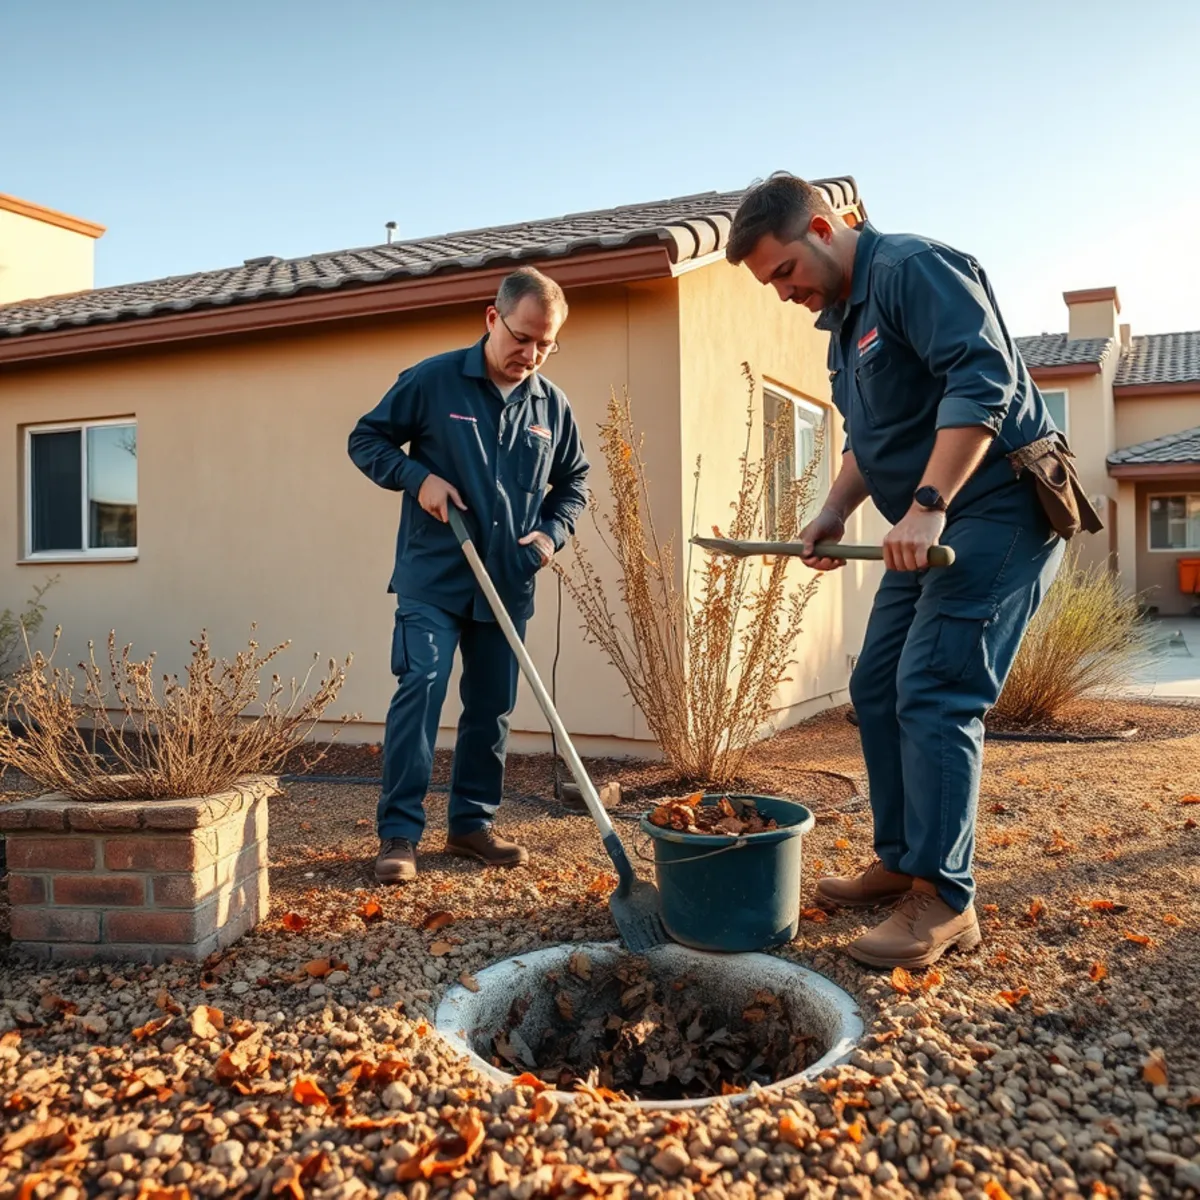
Clear every area drain, yard drain and downspout on the property. Silt and leaf litter accumulate over the dry months and the first storm is when you find out.
Check the grade around the house. If planter soil sits above the slab edge anywhere, regrade it. This is cheap and it is the fix for a surprising share of the storm intrusion we respond to.
Look at your driveway pitch. If it slopes toward the garage, a trench drain or a threshold seal is a permanent solution to a recurring problem.
Clean gutters and confirm downspouts discharge away from the foundation rather than beside it.
And price a flood policy. Thirty-day waiting period means October is the last reasonable month to make that decision.
From the field
What actually floods in Irvine, and why the map misses it
The flooding we respond to here is rarely a creek jumping its banks. It is drainage capacity. In an atmospheric river event, local storm drains and the channels they feed are at capacity simultaneously, water stops leaving streets at the rate it arrives, and it ponds — then finds the lowest thresholds: garage aprons, side doors, subterranean parking ramps and sunken patios. UC Irvine researchers have made exactly this argument, that private and public flood models understate urban Southern California exposure because they were built around riverine and coastal flooding.
Practically, that means being outside a mapped hazard zone tells you what FEMA modelled, not what your street does when four inches falls in a day. The properties we see affected are frequently outside mapped zones and share a different set of features: a low point on the block, a driveway that slopes toward the house, a garage threshold barely above grade, or a subterranean level below street elevation.
The useful side of that: properties outside mapped zones qualify for preferred-risk NFIP policies, which are inexpensive precisely because the mapping says the risk is low. We do not sell insurance and have nothing to gain from that recommendation. What we see consistently is that the uncovered losses are the surface-water ones, and their owners had never priced flood coverage because nobody told them they should.
Walk your lot during a real storm, once
Where does water actually go? Ten minutes in the rain tells you more about your property than any map, and it shows you which threshold is the low one.
NFIP has a thirty-day waiting period
Buying as a storm approaches does not work. October is the month to price it, not January.
Frequently Asked Questions
Is my Irvine home in a flood zone?
Check FEMA's Flood Map Service Center for your specific address — that is the official designation and it is what a lender uses. Be aware that research from UC Irvine argues these models understate drainage-driven urban flooding, so being outside a mapped hazard area is not proof you cannot take on water in a hard storm.
Does homeowners insurance cover storm flooding in Irvine?
No. Standard California policies exclude flood entirely — surface water, runoff, rising water and mudflow. That requires a separate flood policy with a 30-day waiting period after purchase. Storm damage that breaches your structure first, such as rain through a wind-damaged roof, is treated differently and is often covered.
What is the cheapest way to reduce my flood risk?
Clear every area drain and downspout before November, and check that the finished grade around your house still slopes away from it. Decades of added planter soil quietly raise grade above the slab edge, and that single condition is behind a large share of the storm intrusion we respond to. Both are a weekend and almost no money.
Need help with this in Irvine?
We handle this work every week across Irvine and Orange County. A live dispatcher answers 24/7, gives you an arrival window, and tells you what to do while you wait. Free on-site assessment and written scope before any demolition.
Related services