Restoration Service
Water Damage Insurance Claim Help in Irvine, CA
Documentation taken before anything is touched, a line-item scope written the way adjusters read, and billing sent straight to your carrier.
- On site in 60 minutes, anywhere in Irvine
- IICRC-Certified Crews
- We bill your insurer directly for covered work
Most water damage in Irvine is paid for by an insurer, not by the homeowner. Whether yours is paid in full, paid in part, or argued over for three months comes down almost entirely to what was recorded in the first few hours and how the scope was written.
This is the part of the job we do alongside the drying. We are a restoration contractor, not a public adjuster and not a law firm — we cannot negotiate your settlement or represent you against your carrier. What we can do is produce the evidence and the paperwork the claim turns on, and speak to your adjuster directly so you are not relaying technical questions between two parties.
It costs you nothing extra. It is how every job here is run.
Request Insurance Claim Help
Tell us what happened. We respond within minutes, 24/7.
Know the Signs
When Claim Help Actually Changes The Outcome
Not every loss needs this. These are the situations where the documentation decides the number.
The damage crosses into a second room or a second unit
Once more than one space is affected, the adjuster needs a mapped wet footprint rather than a description. In a condo or townhome it also has to be split per unit, or three carriers end up arguing over one invoice.
You are not sure whether it is sudden or gradual
This single distinction decides most denials. Staining, tide lines, rusted fasteners and established growth are what an adjuster reads as duration — so the readings and photographs taken on day one matter more than anything said later.
Someone has already started cleaning up
Understandable, and it removes the evidence. If materials have gone to the kerb we document what remains, record what was removed and when, and say plainly in the scope what could not be verified.
The carrier wants a scope before approving work
Most do. A one-page total cannot be processed — adjusters match line items to their own estimating software. A scope written in that structure is the difference between approval and a request for more information.
Mould has appeared, or might
Many California policies cap mould remediation at a fixed figure regardless of the overall limit. Knowing your cap before the scope is written changes which decisions make financial sense.
Our Process
How A Claim Runs Alongside The Drying
Nothing here delays the work. Documentation happens while extraction is already running.
- 1
Before anything is touched
Capture the loss as it stands
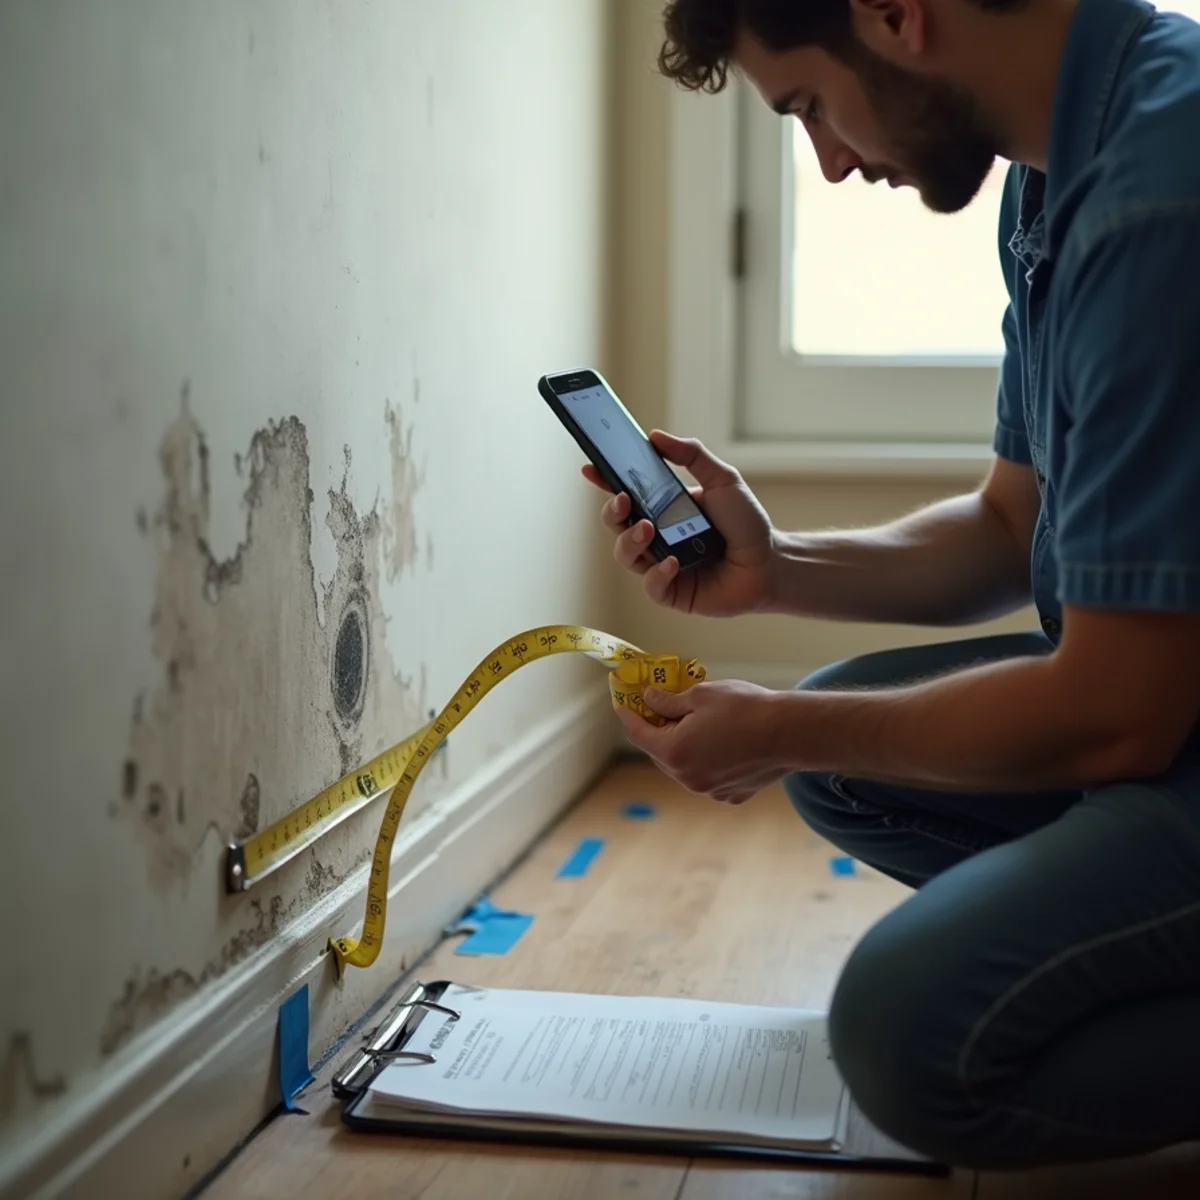
Wide shots of every affected room, close-ups of the source and each wet material, a narrated walk-through video, and moisture readings at marked points. This is the only chance to record the starting condition and it cannot be recreated later.
- 2
First visit
Classify and map
Water category and class recorded, and the real wet footprint mapped with meters and a thermal camera — routinely two to three times the area that is visible. Both belong in the scope because they justify the equipment and the removals.
- 3
Within 24 hours
Line-item scope, split in two
Mitigation and rebuild written as separate documents, because they are priced differently and frequently approved at different times. You get it before any demolition, and it is yours to take to another contractor.
- 4
Throughout
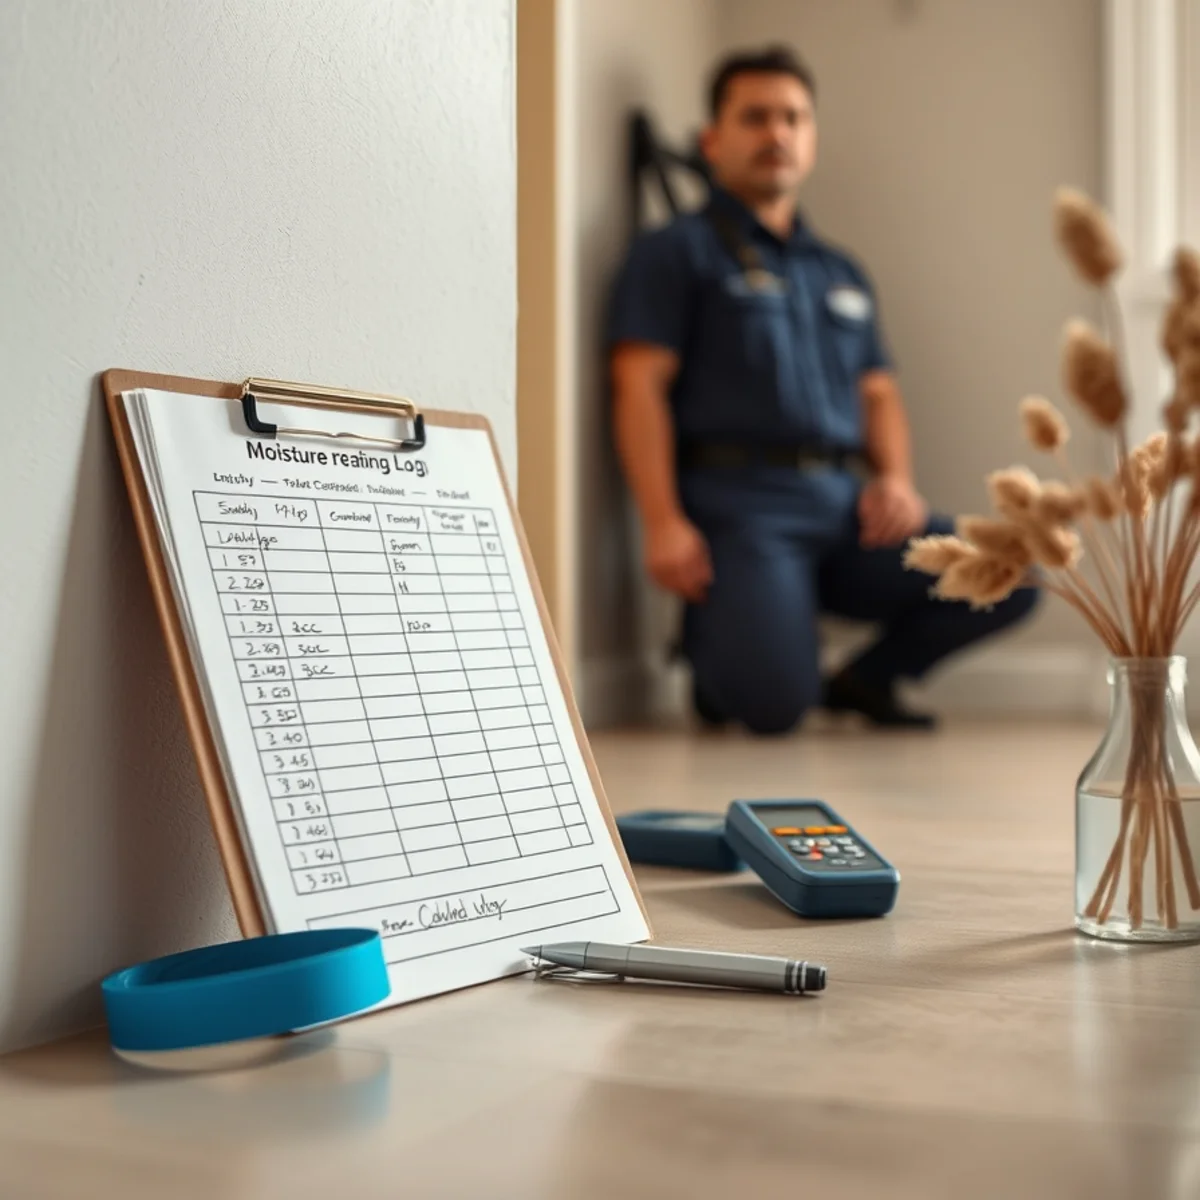
Daily moisture log
Readings at the same marked points every day until materials reach dry standard against an unaffected reference area. This is the document that proves the structure was dried rather than declared dry, and it is the one most contractors cannot produce.
- 5
As needed
Talk to your adjuster directly
Technical questions answered by the person who took the readings. You should not be in the middle translating between a restoration crew and a claims file.
- 6
On covered work
Bill your carrier directly
(201) 277-9344 gets you the details. Direct billing means you are not fronting the whole job and waiting to be reimbursed.
On the Job
Insurance Claim Help in action
What this work actually looks like in an Irvine property.
What Your Policy Probably Covers — And What It Does Not
Most California homeowners policies cover water damage that is sudden and accidental: a supply line that lets go, a failed appliance, a storm that breaches the roof. What they generally exclude is damage that accumulated slowly, and separately, anything that arrived across the ground.
That second exclusion catches people out constantly in Orange County. Surface water, runoff and channel overflow are flood, and flood is excluded from a standard policy at any level — it needs separate NFIP or private cover. The water that comes down through your ceiling in a storm is usually covered; the water that comes in under the garage door usually is not.
The word doing the work in your policy is sudden, and carriers apply it to the failure rather than to your discovery. A pipe that corroded for a decade and burst this morning is still sudden. A drain that has been seeping behind a wall since spring is not.
Report the day you notice, not the day you understand
Prompt notice is a policy condition and late notice is one of the most common grounds for reduced payment. You can report a possible loss before anyone knows the cause.
Check your mould cap before the scope is written
Many policies cap mould remediation at $5,000 or $10,000 irrespective of the overall limit. It is one of the cheapest endorsements to raise and one of the most common shortfalls.
Ask about water and sewer backup separately
Backup through a sewer or drain is excluded from both a standard policy and NFIP flood cover. It needs its own endorsement, and it is usually inexpensive.
Keep every emergency receipt
The after-hours plumber, the hotel, the tarps, the fans bought at midnight. Most policies reimburse reasonable emergency expense and most people throw the receipts away.
Standing water right now? Call us before you do anything else.
We are on site within 60 minutes anywhere in Irvine, 24 hours a day.
What We Will Not Do
There is a lot of overlap in search results between restoration contractors, public adjusters and attorneys, and the three do genuinely different jobs. It is worth being clear about which one you are hiring.
A public adjuster represents you against your carrier and negotiates the settlement, usually for a percentage of it. An attorney handles a dispute that has become legal. We are neither. We dry and rebuild the building, and we produce the technical record that any of those parties would rely on.
We also will not tell you what your claim is worth, promise an outcome, or inflate a scope to improve one. Where a loss looks gradual to us, you will hear that at the assessment rather than from a denial letter — and if what you actually need is a public adjuster, we will say so.
What You Get
What insurance claim help includes
No vague scopes. This is what is actually on the invoice and what you receive at the end of the job.
Photo and video record from before the first piece of equipment runs
Wide, detail and narrated walk-through, timestamped. The backbone of the file and the one thing that genuinely cannot be produced later.
Moisture map of the real affected area
Meter and thermal readings defining the wet footprint, marked on the floor so you can see it. This is the boundary everything else is scoped from.
Line-item scope, mitigation and rebuild separated
Written in the structure adjusters process, delivered before any demolition, and yours to take elsewhere for a second opinion.
Daily moisture log through to dry standard
Readings at the same marked points, dated, measured against an unaffected reference area in your own building.
Equipment record
What was placed, where, and for how many days — the line carriers scrutinise most closely on a mitigation invoice.
Direct billing to your carrier for covered work
You are not fronting the job. Where a deductible or an uncovered portion applies, you are told the figure before the work rather than after.
Why Water Damage Irvine
Why Irvine calls us for insurance claim help
Plenty of companies list this service. These are the things that actually change the outcome on this particular kind of job.
The log is the proof, and we hand it over
Ask any restoration company for the daily moisture log at the end of a job. If they cannot produce one they were guessing — and so was your claim.
We scope in the format adjusters actually use
A blended one-page total is not obstruction on the carrier's part; it genuinely cannot be processed against their estimating software.
One company from extraction to final paint
When drying and rebuild are two contractors there is a handover in the middle that neither owns and no adjuster likes. Here it is one scope and one accountable party.
We say when a loss looks gradual
You will hear our honest read at the assessment. We would rather lose the job than have you find out from a denial letter weeks later.
Honest Pricing
What Claim Support Costs
Nothing additional. Documentation, the scope, the moisture log and talking to your adjuster are part of how the job is run, not a line item on top of it.
What you pay is the restoration work itself, and on a covered loss that is billed to your carrier directly. In practice your out-of-pocket is your deductible plus anything the policy genuinely does not cover.
Your deductible
Applies to every covered claim. On a small loss it is worth comparing it against the repair cost before filing at all — we will give you an honest number to make that call.
Your mould cap
Often $5,000 to $10,000 regardless of the overall limit. If remediation is involved, this figure shapes what is worth doing.
Covered versus excluded cause
Sudden and accidental is usually covered; gradual damage and surface water usually are not. The cause determines the whole conversation.
Whether an assessment was ever ordered
Claims where nobody mapped the wet area are the ones that get reduced, because the carrier has no basis for the larger figure.
A note on estimates: Free on-site assessment and a written scope before any demolition. Call (201) 277-9344 and we will tell you honestly which side of the covered line your loss appears to fall on.
Local Coverage
Water Damage Insurance Claim Help across Irvine and Orange County
Same crews, same equipment, same 60-minute commitment across Irvine. Pick your neighborhood or city for the local detail.
Irvine Neighborhoods
Nearby Cities
Questions
Insurance Claim Help — Frequently Asked
Do you handle the insurance claim for me?
We handle the technical half of it — the documentation, the moisture readings, the line-item scope and direct billing, and we speak to your adjuster so you are not relaying questions you were never meant to answer. What we cannot do is negotiate your settlement or represent you against your carrier. That is a public adjuster's role, and we will tell you if we think you need one.
Does using your own contractor affect my claim?
In California you choose your own restoration contractor. A carrier may suggest a preferred vendor, and you are free to use them or not. What matters to the claim is the quality of the documentation and whether the scope is written in a format the adjuster can process — not whose list the contractor appears on.
Should I file a claim if the damage is close to my deductible?
Often no, and we will say so. If the repair lands near your deductible you may be paying most of it anyway while putting a claim on your record. The honest way to decide is to get the assessment and the written scope first, then compare the real number to your deductible. The assessment is free either way.
What if my claim has already been denied?
Get the denial in writing and read the stated reason — most denials turn on the sudden-versus-gradual distinction or on a flood exclusion. If the loss was genuinely sudden and the file simply lacked evidence, moisture readings and a proper scope can support a reconsideration. If the cause really is excluded, no documentation changes that, and you are better served by a public adjuster or an attorney than by us.
How soon do I need to report water damage to my insurer?
The same day you notice it. Prompt notice is a condition of most policies, and delay is one of the most common reasons a payment gets reduced. You do not need to know the cause or the cost to report — a short call saying you have discovered water and are getting it assessed is enough to protect the claim.
Local Proof
What customers say
Read verified customer reviews on our Google Business Profile.
“Our water heater went at 4 a.m. and the garage was under an inch of water. A real person answered, told me exactly which valve to close, and a crew was here before 5. They stopped it reaching the hallway.”
Water Heater Leak Cleanup
“We had a warm patch on the kitchen floor for weeks and assumed it was nothing. They found the slab leak in about twenty minutes without opening a single tile, and the report went straight to our adjuster.”
Slab Leak Detection
“Another company told us the whole plaster ceiling had to come out. These guys dried it in place over six days and the room looks exactly like it did. On a 1912 house that matters.”
Structural Drying
Testimonials shown are illustrative placeholders pending verified customer reviews and are not marked up as structured review data. More about our reviews
Related services
Water Damage Restoration
Extraction, structural drying, mold prevention and full rebuild — one crew, one contract, billed straight to your insurer.
Read moreMold Remediation
Containment, HEPA-filtered removal and moisture correction — because mold that grows back was a water problem, not a mold problem.
Read moreStorm Damage Cleanup
Emergency tarping and board-up first, then extraction, drying and repair — before the next band of the storm arrives.
Read more
Read next
How to Document Water Damage for an Insurance Claim (Photo & Receipt Checklist)
Your claim will be decided on evidence created in the first hours. Here is exactly what to capture before anything gets cleaned up.
Read moreDoes Homeowners Insurance Cover Water Damage in California? What's In and What's Out
Most water damage disputes come down to one word: sudden. Here is what that means in practice and how to stay on the right side of it.
Read moreFlood Insurance vs. Homeowners Insurance: Why Storm Flooding Usually Isn't Covered
Rain through a wind-damaged roof: usually covered. The same rain coming under your garage door: usually not. The distinction is worth understanding before it rains.
Read more
24/7 live dispatch
Water Damage Insurance Claim Help in Irvine, CA — 60 minutes away
Call (201) 277-9344 and a live dispatcher will give you an arrival window on that call. Free on-site assessment and written scope before any demolition.
- Free on-site assessment and written scope before any demolition
- Fully insured — general liability and workers' compensation